

Barclays US

- 7.15K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on Barclays US from Appgk
Barclays US is the kind of finance app I would recommend to someone who already uses Barclays and wants a practical way to keep an eye on their money without opening a laptop. My overall impression is positive: it puts everyday account management in a compact mobile experience, feels approachable for routine checks, and has earned a strong 4.6 average from around 60 thousand ratings. The important qualification is that its value depends heavily on whether Barclays is already part of your financial life. It is a useful companion for existing customers, but it is not a general-purpose budgeting app or a replacement for a broader financial dashboard.
The app is developed by Barclays US and is free to download. It belongs firmly in the personal finance category, with an Everyone age rating, and it has been available since 2012. The current release is version 8.7.2 and requires iOS or Android 12 or a later operating system. Those details matter in practice: the app is aimed at ordinary account holders rather than a specialist investing audience, but anyone using an older phone should check compatibility before planning around it.
What using Barclays US feels like day to day
The strongest part of a banking app is rarely a flashy feature. It is the ability to answer small money questions quickly and confidently. When I open Barclays US, I expect to use it for the same short tasks I would otherwise postpone: checking whether a payment has cleared, reviewing recent activity, confirming that a balance looks right, or handling an account-related action while away from a computer.
That makes the app most useful as a regular checkpoint rather than something I would browse for entertainment. A quick morning check can confirm that an expected deposit arrived. Before making a large purchase, I can review the available balance instead of relying on memory. At the end of the week, looking through recent transactions can reveal a forgotten subscription or a payment that was larger than expected. These are simple habits, but mobile access makes them much easier to maintain.
Best Parts of Barclays US
Things to Keep in Mind About Barclays US
I also like the psychological benefit of having routine financial information close at hand. People often avoid checking accounts because the process feels like a chore. A dedicated app lowers that barrier. The experience is more immediate than signing in through a browser, and the phone format suits short sessions. I would not describe it as a complete financial planning system, but it does a good job of supporting the small decisions that keep an account under control.
The store summary calls the experience safe, convenient, and rewarding. I would treat those words as a broad description rather than a reason to install it by themselves. The more convincing evidence is how well the app fits a real Barclays customer’s routine. If your main need is access to your Barclays relationship while travelling, shopping, or managing household bills, the convenience is tangible. If you want to combine several banks, analyze spending categories, or build a detailed long-term plan, the app’s role is narrower.
News and Features Related to Barclays US

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic household example
Imagine I am waiting for a salary payment before paying several bills. Instead of repeatedly checking a desktop website, I can open the app during a commute or while preparing dinner, look at the latest account activity, and decide whether the timing is right. Later, I might use another short session to confirm that a scheduled payment has appeared. The value is not that the app transforms personal finance; it is that it removes unnecessary friction from decisions I already need to make.
For a couple or family, that same workflow can help with basic coordination. One person can check whether a payment has gone through before the other moves money or makes a purchase. It is still important to agree on how the household tracks spending, because a banking app alone will not explain every financial goal. However, quick access to current account information can prevent avoidable misunderstandings.
Don't want to read the full review?
Where the app earns trust
A finance app has to make routine information feel dependable. I pay attention to whether the presentation encourages careful checking rather than impulsive action. Barclays US works best when I use it as a clear reference point: open it, verify the relevant detail, complete the necessary task, and close it. That focused pattern is preferable to an interface that buries account information under promotions or unnecessary distractions.
The app’s popularity also gives some useful context. It has passed one million installs and has collected roughly seven thousand written reviews, so it is not an obscure experiment with a tiny user base. A large audience does not guarantee that every person will have a smooth experience, but it does suggest that the app is being used as a mainstream mobile banking tool rather than only by early adopters.
Screenshots
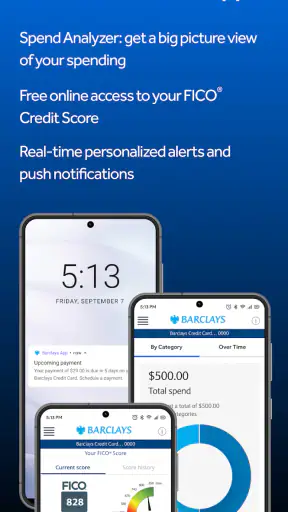
One practical tip is to decide in advance what you want to check before opening it. For example, I might be looking only for a cleared payment, a current balance, or recent activity. This sounds obvious, but it reduces the chance of turning a quick check into an unfocused session. It also makes it easier to notice something genuinely unusual, because I am comparing the screen with a specific expectation.
Useful habits that are easy to overlook
My first non-obvious recommendation is to use the app as a transaction-audit tool, not merely a balance viewer. A balance can look normal while a recent charge still deserves attention. Reviewing activity after recurring bills, travel, or a busy shopping day gives a more accurate picture of what has actually happened. I would make this a weekly habit rather than waiting until a statement or payment problem forces me to investigate.
Second, I would use it at decision points rather than only on a fixed schedule. Checking before a transfer, before a large card purchase, and after an expected deposit creates a simple chain of confirmation. This is more useful than opening the app many times without a purpose. It also helps separate available money from money that is already mentally committed to bills or savings.
Third, I would keep a separate note of financial goals if those goals matter to me. Barclays US can be the place where I verify account activity, but I would not rely on a banking feed alone to explain whether I am progressing toward an emergency fund, a holiday budget, or debt reduction. A small personal spreadsheet or notes system can add the planning layer that a focused banking app does not provide. That combination is often more effective than expecting one app to do everything.
There is another useful trade-off here. A dedicated bank app can be less cluttered than an all-in-one money manager because it focuses on the Barclays relationship. That simplicity is a strength when I want current account information. It becomes a weakness when I need a complete view across institutions. Before installing it, I would ask whether my problem is access to Barclays or lack of financial organization across several providers. The answer determines whether this app is the right tool.
The main limitation: its usefulness is naturally narrow
The biggest weakness is not necessarily a missing button; it is the boundary of the product. Barclays US is designed around Barclays US customers. Someone who wants a neutral service for multiple banks, detailed spending analysis, or a unified household dashboard may find the experience too specialized. In that situation, a dedicated budgeting application or the individual apps from several financial institutions may be a better fit, even if that setup is less convenient in other ways.
I would also avoid treating the app as a substitute for careful financial judgment. A mobile screen can make account information easy to reach, but it cannot decide whether a purchase fits a long-term plan. It cannot replace reading the details of an account action, checking a payment destination, or keeping personal records for important transactions. The convenience is real, but convenience should support attention rather than weaken it.
Another point is device compatibility. The minimum operating system is Android or iOS 12, which is reasonable for many current phones but still relevant to people keeping older hardware for as long as possible. If the app is intended for a family member with an older device, I would check the operating system first and avoid assuming that every phone can run the current release. This is a small preparation step that can prevent frustration.
Security also deserves a sensible approach. I would install the app only through the normal official app marketplace, keep the phone’s operating system updated, use a strong device lock, and avoid signing in over an untrusted connection. Those are not special tricks for Barclays US; they are good habits for any finance application. The app can make access safer and more convenient, but the user still controls much of the surrounding security.
Who will get the most from it?
I think Barclays US is a strong match for existing Barclays customers who prefer managing routine banking from a phone. It suits people who check balances frequently, monitor payments, travel between home and work, or simply want to avoid using a browser for every small task. It is also a sensible choice for users who want a straightforward finance app rather than a large platform full of unrelated planning tools.
It can work well for someone developing better money habits, provided the person understands its role. The app can make checking activity easier and more regular, which is valuable for awareness. I would pair it with a simple spending plan if the goal is to change behavior. Seeing transactions is not the same as categorizing priorities, so the app is best viewed as a reliable window into the account rather than the entire system for managing money.
I would be more cautious about recommending it to a user who does not bank with Barclays US, needs extensive cross-bank reporting, or wants sophisticated investment research. Such a person may be better served by a broader financial-management product or by the relevant provider’s own specialist application. Choosing a popular app is not enough; the account relationship and the desired workflow matter more.
How it compares with common alternatives
Compared with mobile browser banking, the dedicated app should be more natural for repeated short visits. A browser can be perfectly adequate for occasional access, but it adds steps and is less convenient when I simply want to verify recent activity. The app’s advantage is not necessarily a deeper financial analysis; it is a more direct route to the Barclays experience.
Compared with a budgeting app, Barclays US has a different purpose. A budgeting tool may be stronger for categories, goals, trends, and combining accounts, while this app is the more appropriate place to check information at its source. I would not choose between them as if they were identical products. For many users, the best arrangement is the bank app for immediate account truth and a separate planning method for interpreting that information.
Compared with using several banking apps, it can be simpler when Barclays is the main relationship. The trade-off is that simplicity disappears if my finances are spread across multiple institutions. In that case, an aggregator may offer a more complete overview, though I would weigh convenience against the importance of keeping financial access concentrated in trusted services. Barclays US wins on directness, not universal coverage.
My final recommendation
After looking at the app as an everyday finance tool, I see a clear thesis: Barclays US is worthwhile because it makes Barclays account access easy to fit into ordinary routines, not because it tries to become every financial tool at once. Its free price, broad availability, and established user base make it an easy choice for the right customer. The strong average rating supports that impression, while the app’s focused purpose explains why it may not satisfy people seeking a complete money-management suite.
I would recommend it to a Barclays US customer who wants convenient mobile access, regular transaction awareness, and a simple way to make quick account checks. I would skip it as a primary solution if my main requirement were multi-bank budgeting, detailed financial planning, or specialist investment features. In my view, the best way to use it is deliberately: check before important decisions, review activity regularly, and keep a separate plan for goals that go beyond the account itself.
My bottom line: Barclays US is a practical companion for Barclays customers, with enough everyday value to justify keeping it on the phone. It is focused rather than all-encompassing, and that is both its strongest quality and its clearest limitation. If that focused access matches the way you manage money, I would recommend giving it a try; if you need a full financial command center, look for a broader tool instead.
Barclays US FAQ
What is Barclays US, and what can I use the app for?
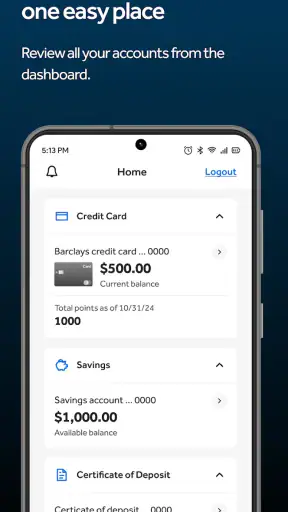
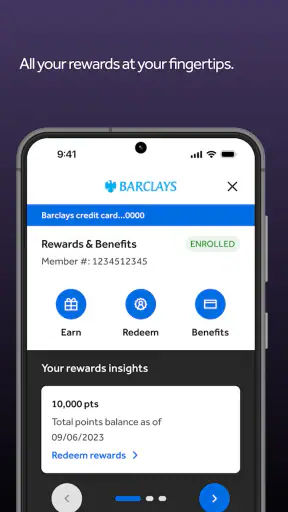
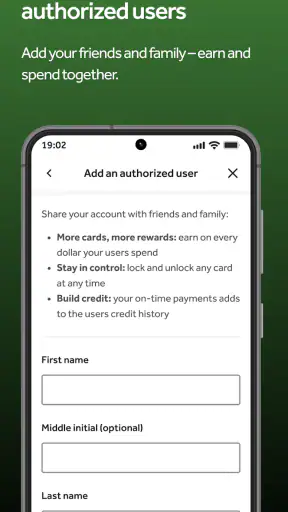
Barclays US is a mobile banking app designed for customers with eligible Barclays products, particularly Barclays credit cards and associated accounts. After signing in, you can review balances, check available credit, view transactions and statements, make payments, manage account alerts, and contact support. The exact features available depend on your specific Barclays account and the services offered to your card.
Is the Barclays US app safe to use for banking and card management?
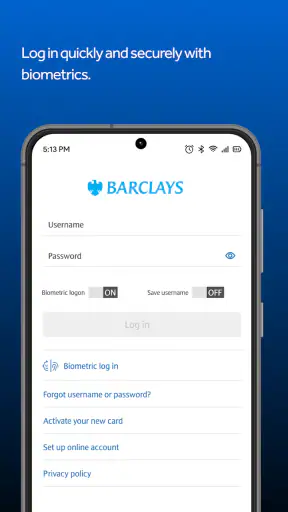
The Barclays US app includes standard security features intended to protect your financial information, such as account authentication, encrypted connections, device verification, and alerts for account activity. You should still use the official app-store version, keep your phone’s operating system updated, avoid public Wi-Fi for sensitive actions, and never share your password, verification codes, or full card details with anyone.
Can I make payments through the Barclays US app?
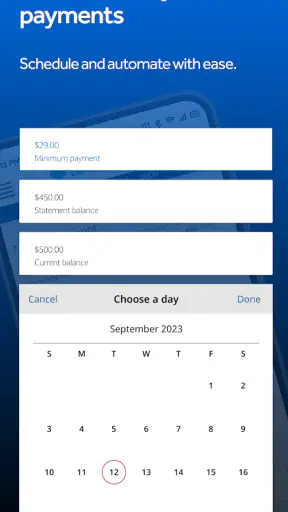
Yes, eligible customers can generally use the Barclays US app to make payments toward their Barclays credit card account. The app typically allows you to select a payment amount, choose an available linked bank account, schedule a payment, and review payment status or history. Processing times and cutoff rules can vary, so check the confirmation details carefully and allow sufficient time before your due date.
Does Barclays US provide transaction alerts and account notifications?
The app may provide notifications for purchases, payment reminders, payment confirmations, balance changes, and other account activity, depending on your account and notification settings. These alerts can help you identify unauthorized transactions quickly and avoid missed payments. After installation, review the available alert options and enable push notifications, email alerts, or text messages according to your preferences.
What should I do if I cannot sign in or notice an unfamiliar transaction?
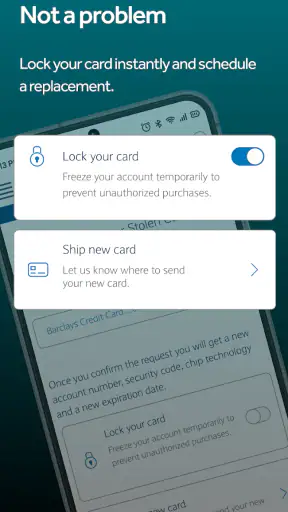
If sign-in fails, first check your internet connection and confirm that you are using the correct Barclays credentials. Use the official password or username recovery options rather than repeatedly guessing. If you see an unfamiliar transaction, lock or secure the card if that option is available, review the transaction details, and contact Barclays through the in-app support tools or the official customer-service number as soon as possible.











